
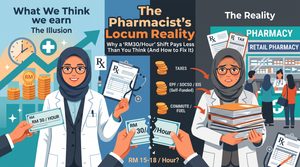
It is 8:30 AM on a Sunday. While most of your civil service colleagues are resting or spending time with family, you are clocking in for an 8-hour locum shift at a retail pharmacy counter.
For many Ministry of Health (KKM) pharmacists under the Public Service Remuneration System (SSPA Gred UF9 hingga UF14), weekend locum shifts are an established part of life.
The rationale seems practical:
- Your government basic salary and civil service allowances are reliable, but fixed.
- Working two Sunday shifts a month at the prevailing market rate of RM30 per hour brings in an extra RM480 to RM720 in gross cash flow.
- It feels like a productive way to cover petrol, pay for weekend dining, or add a buffer to your savings.
However, many KKM pharmacists overlook a fundamental tax rule: locum earnings do not sit in a vacuum—they are added on top of your taxable civil service income, meaning every single ringgit is taxed at your highest marginal rate.
When you factor in progressive income tax, commuting costs, and daily meals, that headline rate of RM30 per hour quietly shrinks to something much smaller.
“Trading a rest day for locum income only builds wealth if that money is protected from tax drag and converted into compounding assets. If your weekend shifts are simply subsidizing lifestyle spending, you are trading your clinical energy and health for barely twenty ringgit an hour.”
The Mathematics of the Marginal Tax Drag
To understand your real hourly earnings, look at how the Inland Revenue Board of Malaysia (LHDN) assesses your income.
As a government pharmacist in Gred UF9 (entry level) or UF10, your monthly payslip includes basic pay along with allowances such as the Bayaran Insentif Perkhidmatan Kritikal (BIPK), Imbuhan Tetap Perumahan (ITP), and Imbuhan Tetap Khidmat Awam (ITKA)/Imbuhan Tetap Keraian (ITK).
Because certain civil service allowances are not taxable and statutory reliefs (individual relief of RM9,000, EPF/SOCSO, and lifestyle) reduce your total chargeable income, most early-to-mid career KKM pharmacists sit comfortably in the 11% or 19% marginal tax bracket:
- Chargeable Income RM50,001 to RM70,000: Marginal tax rate of 11%
- Chargeable Income RM70,001 to RM100,000: Marginal tax rate of 19%
[ Primary Government Salary ]  ───► Absorbs all basic tax reliefs (RM0 - 11% bands)
                                              │
[ Every Ringgit of Locum Pay ] ───► Taxed at your top marginal tier (11% to 19%)
Because your standard personal reliefs are already fully utilized by your primary salary, every ringgit earned on a Sunday shift is shaved down by 11% to 19% before you even step back into your car.
Deconstructing the Real Take-Home on an RM30/Hour Shift
Let’s run the actual math for an 8-hour weekend shift paid at RM30 per hour (RM240 gross):
| Cost / Deduction Item | At the 11% Tax Tier | At the 19% Tax Tier |
| Headline Gross Locum Pay (8 Hours @ RM30/hr) | RM 240.00 | RM 240.00 |
| LHDN Marginal Income Tax | -RM 26.40 (11%) | -RM 45.60 (19%) |
| Petrol, Parking & Commute Costs (Est.) | -RM 20.00 | -RM 20.00 |
| Shift Meals & Refreshments | -RM 15.00 | -RM 15.00 |
| Net Disposable Income in Your Pocket | RM 178.60 | RM 159.40 |
| Your True Net Hourly Rate | RM 22.33 / hr | RM 19.93 / hr |
| Total Real-World Value Erosion | -25.6% | -33.6% |
⚠️ The Uncomfortable Truth
While your locum agreement states RM30 per hour, your actual net compensation after tax and basic working expenses sits between RM19.90 and RM22.30 per hour.
You are spending 8 hours on your feet handling prescriptions, managing patient inquiries, and carrying full professional dispensing liability—only to walk away with approximately RM160 to RM180 net for the day.
If that money simply disappears into grocery bills, bubble tea, or impulse online purchases, you are sacrificing your recovery time before Monday hospital rounds for negligible long-term financial gain.
The LHDN Compliance Risk: Form BE vs. Form B
Depending on the structure of your engagement, your locum income may be classified as business income, which requires you to use Form B to report your income tax.
- The Form BE Myth: Many KKM pharmacists continue filing Form BE (Employment Income Only), either omitting locum payments or tucking them into miscellaneous sections.
- The Form B Requirement: LHDN considers regular locum engagements to be independent professional or business income. Legally, recurring locum practitioners must file using Form B (due annually by June 30).
- The CP500 Estimated Tax Notice: Once you report business income on Form B, LHDN will typically issue a CP500 installment notice the following year, requiring advance tax payments every two months. Failing to prepare for CP500 installments leads to unexpected cash crunches and statutory penalties.
Check with a tax agent on your specific arrangement.
Professional Deductions You Can Claim Under Form B
If you file Form B, you are entitled to claim legitimate, verifiable professional expenses directly incurred in generating that locum income:
- Annual Retention Certificate (ARC) renewal fees paid to the Pharmacy Board Malaysia.
- Malaysian Pharmaceutical Society (MPS) annual membership dues.
- Professional Indemnity Insurance premiums (e.g., MPS-endorsed liability policies).
- Direct Mileage & Commute Logs: Mileage incurred traveling directly between your primary station or home and the locum premise (keep a written logbook and petrol receipts).
- Clinical Seminars & CPD Courses: Registration fees for conferences and training necessary to maintain your active practice credentials.
The Strategic Fix: Turning Locum Hours into Real Wealth
Taking on weekend shifts only makes financial sense if that income is immediately separated from your daily spending and deployed into assets that out-earn your physical labor:
[ Monthly Locum Pay: ~RM 480 - RM 720 ]
                  │
                  ├──► 15%-20%: Transfer to High-Yield Cash Account (LHDN Tax Reserve)
                  │
                  └──► 80%-85%: Automated Wealth Compounding:
                         ├── PRS (Private Retirement Scheme) for direct tax relief
                         └── Voluntary EPF Self-Contribution (compounding at 5.5%+)
💡 The Wealth Multiplier Strategy
Suppose you take the net proceeds of two weekend shifts—approximately RM350 per month—and automate it into a globally diversified index fund compounding at a conservative 7% annual return:
- In 5 Years: You accumulate approximately RM 25,000.
- In 10 Years: You accumulate approximately RM 60,500.
- In 20 Years: You accumulate approximately RM 182,000.
At that stage, your investment portfolio generates enough annual passive dividend income to completely replace your locum shifts, giving you your weekends back without any drop in lifestyle.
Five Practical Rules for KKM Locum Pharmacists
- Quarantine Your Tax Reserve Instantly: The day locum money enters your account, move 15% to 20% into a separate digital cash or money market fund. Never let tax money blend into your daily spending wallet.
- Never Peg Fixed Living Expenses to Locum Income: Your car loan, mortgage, and household bills must be serviceable by your KKM government salary alone. If you need locum pay just to break even each month, you have a structural spending problem, not an income problem.
- Keep Every Professional Receipt: Maintain a dedicated folder for your ARC receipt, MPS dues, liability insurance, and seminar tickets to offset your Form B revenue.
- Use PRS to Wipe Out the Tax Drag: Allocating up to RM3,000 per year into a Private Retirement Scheme (PRS) gives you a dollar-for-dollar personal tax relief that directly offsets your locum tax liability.
- Set an Intentional Target: Decide in advance why you are working locums—whether to build an emergency fund of RM20,000 or fund a child’s education account. Once that milestone is met, reduce your shifts to protect yourself from clinical burnout.
The Verdict: Value Your Time and Clinical Energy
Locum work can be a helpful financial booster for young KKM pharmacists, but only if you are deliberate about the math.
Recognizing that an RM30 headline rate yields around RM20 net per hour changes how you view your schedule. Protect your earnings from unnecessary tax drag, claim your legitimate professional deductions, and channel that hard-earned weekend money directly into long-term compounding assets.
Working Weekend Locums but Not Sure If Your Net Worth Is Truly Moving?
Sacrificing your rest days shouldn’t result in surprise tax notices or feeling stuck on a treadmill. Book a free 30-minute financial review to audit your locum tax structure, calculate your true hourly rate, and build an automated investment roadmap.
Just schedule a meeting by clicking the button below. I will reach out to you and see if we would be a good fit for each other.
Or if you are not ready yet, join my email list to receive useful information to improve your finances by clicking here.
Disclaimer: This page is for informational purpose only. You should use judgment and conduct due diligence before taking any action or implementing any plan suggested or recommended in this article. Speak to a professional about your specific circumstances.
